
I just noticed an REO in Seacrest, originally listed as a short sale for 795K (297 sq. ft.), came back on the market as an REO at 565K (211 sq.ft.) and went under contract in 4 days.
Replies
118
SoWal Insider
So when you bought your house, you didn't care about the things which play into the resale factor?
No...it fit our needs and our budget.
.
Edited
Beach Fanatic
An "investment" is using money for the purpose of making more money. An "investment RISK" is the potential of one's investment to go up or down.
Yes, I believe a primary home IS an expense...one must live somewhere. And unless one is a "investulator," and is leveraged to the eyebrows in a hot housing market, most folks who've been living in their homes a long time and then sell will find that when they add up ALL the costs of primary homeownership...not just Purchase Price - Selling Price = Profit, they've made only very modest returns vs. other asset classes.
.
.
This is what the Book "Rich Dad, poor Dad" is about. Your primary home is a liability. But the author buys other homes with cash for rental income. All monies made are used to establish more rental properties until the income passes your job and you can move into financial freedom! The American dream!

Beach Fanatic
No...it fit our needs and our budget.
.
seems so boring..... Have you not ever had dreams of being the greeter at Walmart?


SoWal Expert
No...it fit our needs and our budget.and since you can afford the home, you don't care at all about the selling price when the time comes to sell?
.
You are a rare breed.
Beach Fanatic
This is what the Book "Rich Dad, poor Dad" is about. Your primary home is a liability. But the author buys other homes with cash for rental income. All monies made are used to establish more rental properties until the income passes your job and you can move into financial freedom! The American dream!Gotta have a wad to start off with it appears. And I am not saying that there are not successful landlords out there but I can not do it successfully, not even as a sideline (even in this "depressed" market). Cash on cash return seems a bit paltry for what I see around. Sounds nice though.
Beach Fanatic
Gotta have a wad to start off with it appears. And I am not saying that there are not successful landlords out there but I can not do it successfully, not even as a sideline (even in this "depressed" market). Cash on cash return seems a bit paltry for what I see around. Sounds nice though.
Read the book. You do not have to have a wad. You have to have time and start real small. It grows with time.
Beach Fanatic
Read the book. You do not have to have a wad. You have to have time and start real small. It grows with time.Will do. I took your synopsis of "But the author buys other homes with cash for rental income.." to mean he buys other houses with cash for rental income and subsequently figured I would need minimum $120,000 or so to get started. That, to me, is a wad. I am too lazy to be a landlord.
Beach Fanatic
There are niche markets for rental properties that will do surprisingly well, even in current conditions. Go get the book where US News ranks colleges & universities. Now look at bottom quintile schools in the middle of rural America nowhere. Now target townhomes and small 3 bedroom single family homes to buy. Should be pretty cheap in many of those places- you're talking $50-$80K for something in a safe area. Put like 30-40% down and finance the rest.
Now rent them out. Not to students, but to young faculty and staff members who are fresh out of grad school, and who don't have the money to buy on their own yet. And at those kinds of schools, there will always be a fresh stream of new young faculty members to rent to because only about half of the new faculty will last more than three years before getting some post grad years in, and moving on to a school with more prestiege or in a bigger area.
In a lot of those towns, you'll get a far, far better ROI than in any place you'd actually want to live, and young professionals are one of the lower risk groups to rent to.
Now rent them out. Not to students, but to young faculty and staff members who are fresh out of grad school, and who don't have the money to buy on their own yet. And at those kinds of schools, there will always be a fresh stream of new young faculty members to rent to because only about half of the new faculty will last more than three years before getting some post grad years in, and moving on to a school with more prestiege or in a bigger area.
In a lot of those towns, you'll get a far, far better ROI than in any place you'd actually want to live, and young professionals are one of the lower risk groups to rent to.
SoWal Insider
and since you can afford the home, you don't care at all about the selling price when the time comes to sell?
...I don't need to care about the selling price when it comes time to sell.
.
Edited
Beach Fanatic
Will do. I took your synopsis of "But the author buys other homes with cash for rental income.." to mean he buys other houses with cash for rental income and subsequently figured I would need minimum $120,000 or so to get started. That, to me, is a wad. I am too lazy to be a landlord.
It really is a good read. I wish I would have been directed in this area at a young age. Being a landlord can be tough but not really to bad if that is all you do.
SoWal Insider
seems so boring..... Have you not ever had dreams of being the greeter at Walmart?
I'm doing just fine....but I think those jobs are now filled with former passengers of the RE gravy train.
.
SoWal Insider
This is what the Book "Rich Dad, poor Dad" is about. Your primary home is a liability. But the author buys other homes with cash for rental income. All monies made are used to establish more rental properties until the income passes your job and you can move into financial freedom! The American dream!
...and we all know how that story ended for quite a few of his "followers." :roll:
.
SoWal Insider
Gotta have a wad to start off with it appears. And I am not saying that there are not successful landlords out there but I can not do it successfully, not even as a sideline (even in this "depressed" market). Cash on cash return seems a bit paltry for what I see around. Sounds nice though.
In too many cases, the 'wad' was produced from HELOCing one's primary residence out the whazoo, then HELOCing the 2nd property to purchase the 3rd property and on and on...but that boat has already sailed. :roll:
.
Edited
Beach Fanatic
uh, ya mean "short sailed" ?
Beach Fanatic
...and we all know how that story ended for quite a few of his "followers." :roll:
.
They took out loans.... You have to follow the instructions.

Beach Fanatic
Serious buyers love this market?
Well, I guess that depends on how risk adverse they are. I know that my tolerance for risk was pretty much wiped out by Katrina. I look at Shelly's list and think "certain we'll live there for five years?" Well, unless there's a horrible hurricane and all the patients move away, or a pandemic makes tourism verboten, or an asteroid crashes into the Yucatan and causes a big tidal wave and all the homes are swept away along with the hospital.
I have made up a list of houses I love, I researched sales in their areas and and I compared those with other "comps" as I see them (which is really what matters when you're looking for a home) -- houses that I like equally well that sold recently in and around SoWal -- when real comps weren't available. I made a list of what I was willing to pay, and then looked to see if the houses were mortgaged up way beyond what I thought was reasonable TO ME. I was left with four houses. As examples, one is listed at $899K, and I LOVE it and think it's a fair buy at $580K, based on recent sales + a bonus of $130K for better view. Another is listed at $595K, and I think a good price on it would be $315K, with no bonus because it's only two bedrooms and if someone were to abandon a child in a basket on our doorstep it would no longer fit every need.
So, big spreads. If that makes me not serious, then so be it. I still plan to try, but if a rental comes along I won't make the mistake of asking for 24 hours to throw out an offer on the most favorite house again. I'm funny like that when it comes to having shelter.
Well, I guess that depends on how risk adverse they are. I know that my tolerance for risk was pretty much wiped out by Katrina. I look at Shelly's list and think "certain we'll live there for five years?" Well, unless there's a horrible hurricane and all the patients move away, or a pandemic makes tourism verboten, or an asteroid crashes into the Yucatan and causes a big tidal wave and all the homes are swept away along with the hospital.
I have made up a list of houses I love, I researched sales in their areas and and I compared those with other "comps" as I see them (which is really what matters when you're looking for a home) -- houses that I like equally well that sold recently in and around SoWal -- when real comps weren't available. I made a list of what I was willing to pay, and then looked to see if the houses were mortgaged up way beyond what I thought was reasonable TO ME. I was left with four houses. As examples, one is listed at $899K, and I LOVE it and think it's a fair buy at $580K, based on recent sales + a bonus of $130K for better view. Another is listed at $595K, and I think a good price on it would be $315K, with no bonus because it's only two bedrooms and if someone were to abandon a child in a basket on our doorstep it would no longer fit every need.
So, big spreads. If that makes me not serious, then so be it. I still plan to try, but if a rental comes along I won't make the mistake of asking for 24 hours to throw out an offer on the most favorite house again. I'm funny like that when it comes to having shelter.

SoWal Expert
IMO serious buyers like this market better than the one a year or two ago because some much needed price reality is appearing, but are frustrated by the short sales and banks.
I would focus much more on what you are willing and able to pay for the home you want and come up with a fair price that way. It's a residence and fulfills a basic need for shelter, it's not a gold brick!
Assessments, comps, and prices are all over the place and I don't feel that I should have to pay more because the seller was greedy and leveraged themselves into a debt much larger than the property is worth with multiple loans and interest only payments.
Think of it as real estate consignment shopping - just because someone once paid inflated retail doesn't mean you have to!
I would focus much more on what you are willing and able to pay for the home you want and come up with a fair price that way. It's a residence and fulfills a basic need for shelter, it's not a gold brick!
Assessments, comps, and prices are all over the place and I don't feel that I should have to pay more because the seller was greedy and leveraged themselves into a debt much larger than the property is worth with multiple loans and interest only payments.
Think of it as real estate consignment shopping - just because someone once paid inflated retail doesn't mean you have to!

SoWal InsiderAuthor
Serious buyers love this market?
Well, I guess that depends on how risk adverse they are. I know that my tolerance for risk was pretty much wiped out by Katrina. I look at Shelly's list and think "certain we'll live there for five years?" Well, unless there's a horrible hurricane and all the patients move away, or a pandemic makes tourism verboten, or an asteroid crashes into the Yucatan and causes a big tidal wave and all the homes are swept away along with the hospital.
I have made up a list of houses I love, I researched sales in their areas and and I compared those with other "comps" as I see them (which is really what matters when you're looking for a home) -- houses that I like equally well that sold recently in and around SoWal -- when real comps weren't available. I made a list of what I was willing to pay, and then looked to see if the houses were mortgaged up way beyond what I thought was reasonable TO ME. I was left with four houses. As examples, one is listed at $899K, and I LOVE it and think it's a fair buy at $580K, based on recent sales + a bonus of $130K for better view. Another is listed at $595K, and I think a good price on it would be $315K, with no bonus because it's only two bedrooms and if someone were to abandon a child in a basket on our doorstep it would no longer fit every need.
So, big spreads. If that makes me not serious, then so be it. I still plan to try, but if a rental comes along I won't make the mistake of asking for 24 hours to throw out an offer on the most favorite house again. I'm funny like that when it comes to having shelter.
I see spreads like that all over the place rapunzel, so you are not alone. I'm also a believer in Shelly's list so I won't be buying unless these prices come down. The foreclosures I am seeing are going for the lower rates, so it will be interesting to see what happens over the next year or so.
One suggestion I will throw out is that as buyers who do not want to throw money away, we need to be patient. This market is moving very slowly, a majority of owners here were not subprime, they have these variable rate arms. A majority of which have not reset yet. When these home loans do reset, a solid percentage of the owners do go into distress and ultimately sell short or go into foreclosure. It's just not going to happen over night. Nobody in their right mind wants to show up at a home sale with a 300K loan check ready to hand over. I can understand why a lot of these folks are holding on, dropping prices slowly and hoping for the best. I'd be doing the same thing in their shoes.
Beach Lover
things are about to get worse
I had thought I might act on a Watercolor short sale and got a pre-approval letter from bank of america, who I have always used. This was in early May and was quoted 7.5% with 0 points for 30 years and 20% down on a Jumbo. Turns out it was so tied up in the foreclosure process that not even the lender could get the process moving. So I have found another property I am interested in and got a new pre-approval letter this week. I was informed that Panama City-Destin area is now classified by BOA as a declining value market and that the rate is now 8.5% with 0 points for a 30 year JUMBO and it requires 25% down. My credit score was 748, so this is as prime as it gets. This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.
I had thought I might act on a Watercolor short sale and got a pre-approval letter from bank of america, who I have always used. This was in early May and was quoted 7.5% with 0 points for 30 years and 20% down on a Jumbo. Turns out it was so tied up in the foreclosure process that not even the lender could get the process moving. So I have found another property I am interested in and got a new pre-approval letter this week. I was informed that Panama City-Destin area is now classified by BOA as a declining value market and that the rate is now 8.5% with 0 points for a 30 year JUMBO and it requires 25% down. My credit score was 748, so this is as prime as it gets. This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.
Beach Fanatic
When these home loans do reset, a solid percentage of the owners do go into distress and ultimately sell short or go into foreclosure. It's just not going to happen over night. Nobody in their right mind wants to show up at a home sale with a 300K loan check ready to hand over. I can understand why a lot of these folks are holding on, dropping prices slowly and hoping for the best.
This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.
I'm no expert by any stretch, but IMHO I do believe it will get worse (for sellers) before it gets better.
SoWal Insider
I had thought I might act on a Watercolor short sale and got a pre-approval letter from bank of america, who I have always used. This was in early May and was quoted 7.5% with 0 points for 30 years and 20% down on a Jumbo. Turns out it was so tied up in the foreclosure process that not even the lender could get the process moving. So I have found another property I am interested in and got a new pre-approval letter this week. I was informed that Panama City-Destin area is now classified by BOA as a declining value market and that the rate is now 8.5% with 0 points for a 30 year JUMBO and it requires 25% down. My credit score was 748, so this is as prime as it gets. This has happened this month and has not had an effect on the housing prices, but finding a buyer may have just gotten alot harder if noone can qualify or afford a mortgage.
The interest rates are on the rise and the Fed can't do jack about it.
My old pal Mike Morgan commented on the recent "Upbeat Pending Home Sale Stats" on his blog:
"In fact, here’s why the recent PHS number is actually very ugly. A PHS simply means there is a contract on the property, but it does NOT mean the property will close. In fact, we no longer write contracts for residential Buyers unless we are 100% sure they will obtain financing or they pay us a $200 fee for writing the contract. The majority of the contracts we have been writing and seen written, do not close. I can safely say the number of deals that don’t make it to closing is at a record high. And that is what you need to focus on.
Lollipops - Even when a Buyer walks into our offices with a pre-qualification letter, it does not mean they will get financing to close. There are a dozen more hoops to jump through, so lenders and mortgage brokers hand out pre-qual letters like they hand out lollipops to kiddies to keep them quiet. Get it? Same thing here, just a different piece of candy.
Last Minute Deal Breakers – Just days before a closing, lenders are now ordering a second or third appraisal. They want to make sure the market has not collapsed further since they offered the mortgage. I’ve had deals fall apart three days before closing, because the lender either wants more down or they are not willing to lend based on the sale price.
---------------------------------------------------------------
No bottom to see here folks...keep moving along.
.
Edited
SoWal Insider
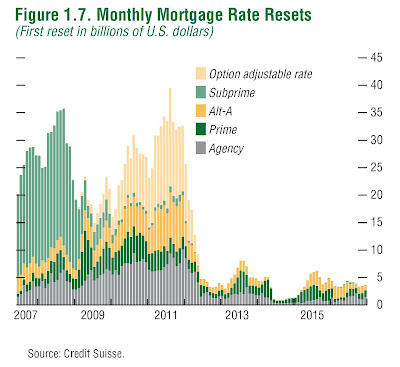
This market is moving very slowly, a majority of owners here were not subprime, they have these variable rate arms. A majority of which have not reset yet. When these home loans do reset, a solid percentage of the owners do go into distress and ultimately sell short or go into foreclosure. It's just not going to happen over night.
Not overnight...looks to be 2010-2011, but I'm betting that lots of these will reach their 125% of principle balance before then...and then the resets will begin to leave their mark.
.
SoWal InsiderAuthor
Not overnight...looks to be 2010-2011, but I'm betting that lots of these will reach their 125% of principle balance before then...and then the resets will begin to leave their mark.
.
BusinessWeek published a good article recently on the subject of arms, they had a nice graph that showed the changes in resets based on that very problem -

http://www.businessweek.com/lifestyle/content/jun2008/bw2008065_526168.htm
SoWal Insider
BusinessWeek published a good article recently on the subject of arms, they had a nice graph that showed the changes in resets based on that very problem -
http://www.businessweek.com/lifestyle/content/jun2008/bw2008065_526168.htm
...and the hits just keep on coming.
Interesting chart...all I can think of is that the blue lines, that tracked the original resets, now predict the schedule of personal bankruptcy filings.
Do you think people are learning anything from outcome of this mess? All the infomercials are about "Making a Fortune in Dealing in Foreclosed Properties." Gawd! I'd give my kingdom just to see Chef Tony plug the Rotato Express again!
Edited
Beach Lover
Short Sales: A Tough Road - LA Times
"RESIDENTIAL short sales sound like a picnic: Owners need to sell their homes for less than they owe, lenders forgive the difference and buyers grab a good deal.
If only. This is one picnic that requires a long wait for dessert. The only "short" thing about short sales, buyers and sellers say, is one's patience."
http://www.latimes.com/news/la-re-shortsale15-2008jun15,0,4015974.story
"RESIDENTIAL short sales sound like a picnic: Owners need to sell their homes for less than they owe, lenders forgive the difference and buyers grab a good deal.
If only. This is one picnic that requires a long wait for dessert. The only "short" thing about short sales, buyers and sellers say, is one's patience."
http://www.latimes.com/news/la-re-shortsale15-2008jun15,0,4015974.story
Checking your forum account
Please wait while we verify your forum account.